Semi-Commercial Property Finance
Semi-commercial property finance is used where commercial and residential elements sit within the same security and need to be assessed separately before being brought together into one workable structure.
Minimum semi-commercial property finance facility: £350,000
Not quite commercial. Not quite residential.
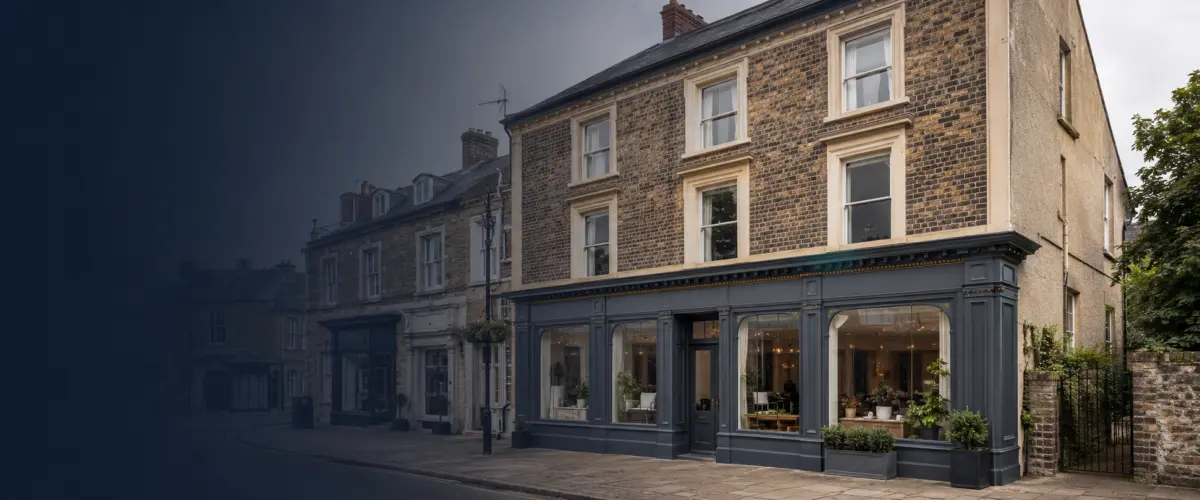
Semi-commercial property sits between the two. A shop with a flat above, an office with residential accommodation or a small mixed-use parade cannot always be assessed properly as either a standard commercial mortgage or a conventional buy-to-let case.
Commercial element
The lender considers the commercial lease, tenant covenant, sector, lease term, rent, vacancy and alternative demand for the commercial space.
Residential element
The lender considers the residential tenancy, sustainable rent, configuration, access and whether that part of the property can support its share of the borrowing.
A mixed-use property can look strong when the income is blended together but still fail if one component is weak on its own. The transaction should therefore be structured from the two underlying parts outward, not forced into a single-product template.
Where semi-commercial property finance is commonly used
Shop with flat above
One of the most common mixed-use structures, particularly where the residential unit is separately accessed and separately let.
Office with residential accommodation
Properties where part of the building is occupied or let commercially and another part provides self-contained residential space.
Small mixed-use parade
Several commercial units with flats above, where tenant concentration, lease expiry and residential income need to be considered together.
Hospitality or takeaway with accommodation
Specialist cases where the commercial use, tenant covenant and residential configuration can materially affect lender appetite.
What semi-commercial lenders will look at
Lender appetite is driven by more than headline LTV. The balance between the two uses, the quality of each income stream and the ease with which the property could be sold or relet all matter.
Commercial/residential split
The proportion of value and income attributable to each use can determine which lenders are available and how they assess the case.
Commercial lease
Tenant covenant, lease term, breaks, rent, arrears and sector all influence the strength of the commercial income.
Residential rent
The residential element may be assessed independently for sustainable rent, tenancy structure, configuration and marketability.
Valuation & vacancy
Vacant commercial space, specialist use or a difficult layout can reduce value and narrow lender appetite materially.
The same property can be assessed very differently by different lenders.
| Issue | What the lender may consider |
|---|---|
| Loan-to-value | Driven by the overall property, but lender appetite can reduce as the commercial proportion or specialist-use risk increases. |
| Commercial element | Tenant covenant, lease length, sector, rental income, vacancy and alternative commercial demand. |
| Residential element | Tenancy, sustainable rent, access, configuration and the marketability of the residential accommodation. |
| Vacant commercial space | Usually weakens affordability and valuation and may require a credible letting strategy or short-term stabilisation finance. |
| Valuation | The valuer may distinguish commercial and residential components rather than rely on one blended value. |
| Borrower structure | SPV, limited company, individual ownership, experience and wider portfolio position may all affect lender choice. |
Split the deal first. Select the lender second.
Understand the property
We establish the commercial use, residential configuration, title, access, leases, rents and funding requirement.
Assess each income stream
Commercial and residential income are considered separately so weaknesses are visible before the case reaches a lender.
Match lender appetite
The case is directed towards lenders that genuinely accept the actual commercial/residential split and property use.
Present the structure
The lender receives a coherent explanation of valuation, income, vacancy, borrower structure and the proposed repayment basis.
The risks that can weaken a mixed-use case
Vacant commercial unit
Absent rent weakens both affordability and investment value and can substantially narrow the lender pool.
Short or weak lease
Lease expiry, breaks, arrears or a weak tenant covenant can undermine the commercial part of the security.
Poor access or configuration
Shared access, unusual layouts or residential accommodation that is not genuinely self-contained can reduce lender appetite.
Specialist commercial use
Takeaways, pubs and other specialist-use premises can have narrower alternative demand and may be valued more conservatively.
Over-reliance on blended income
Strong total rent does not compensate automatically for one element failing its own lender test.
Wrong lender category
Sending the case to a pure BTL or wholly commercial lender can waste time if their policy does not accommodate mixed-use security.
Frequently asked questions
Discuss a semi-commercial property
For semi-commercial property finance requirements of £350,000 or more, send the property type, commercial use, residential element, leases, rents, approximate value and borrowing requirement. We can then consider which lenders are likely to fit the actual structure.
This page is produced for general information about commercial and semi-commercial property finance and does not constitute personal financial advice. EAS Finance is a trading name of Elite Admin Services Ltd (FRN 1044838), appointed representative of White Rose Finance Group Ltd (FRN 630772), authorised and regulated by the Financial Conduct Authority. EAS Finance is a credit broker, not a lender.